
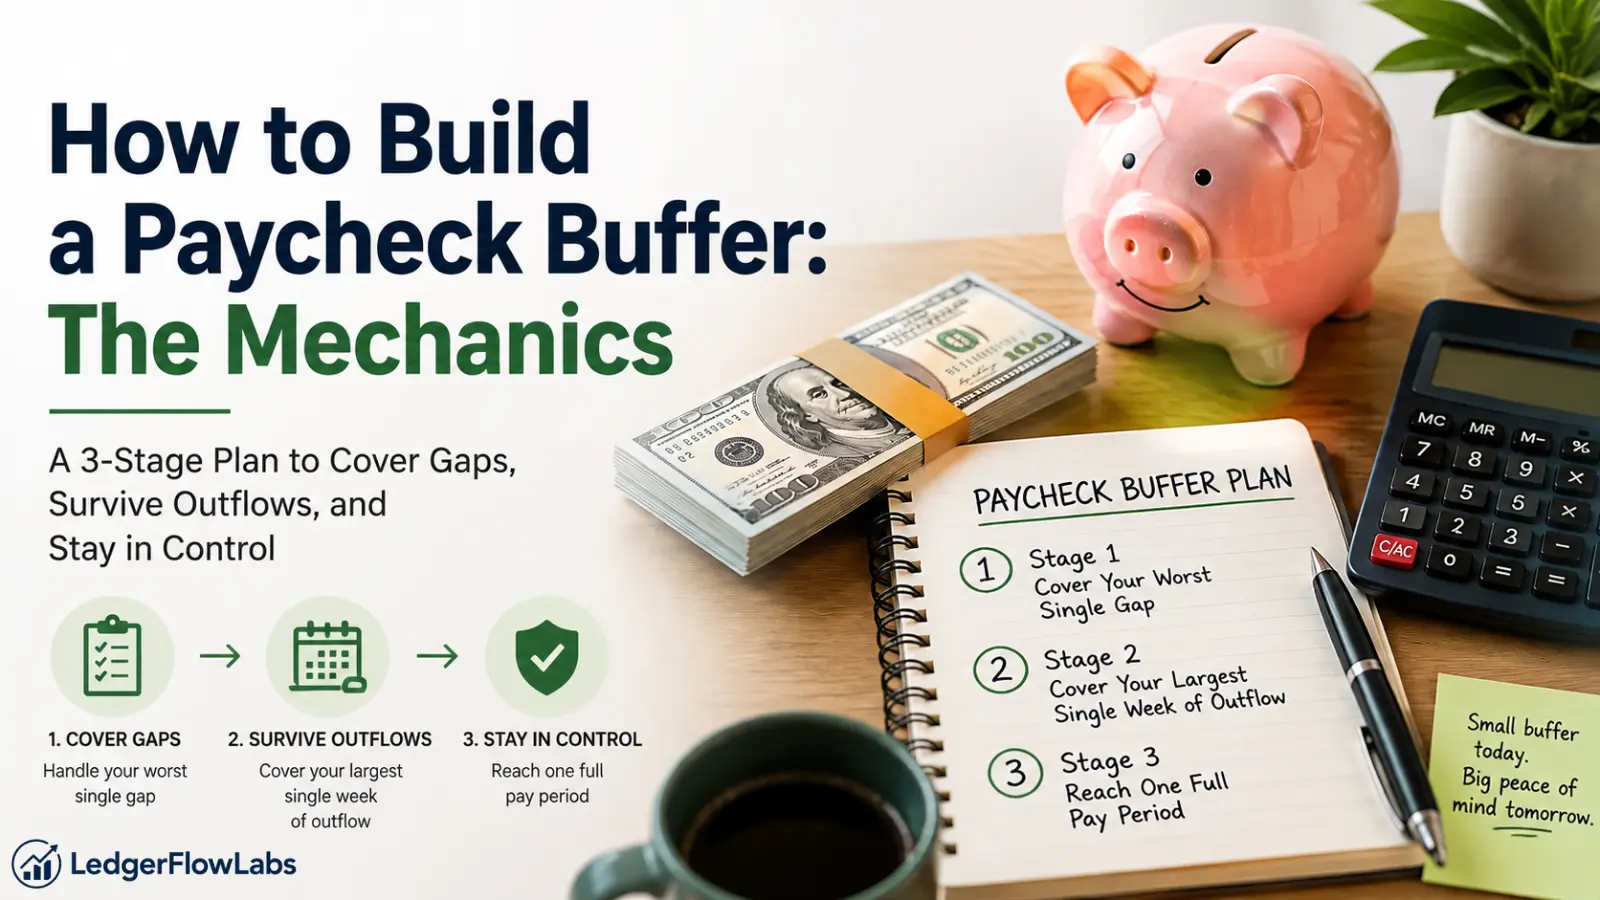
Short answer: a paycheck buffer is money that sits in your checking account permanently so that every payment you make is drawn against money that already arrived, instead of money that is about to. You build it in three stages: first cover your worst single gap between a bill and a deposit, then cover your largest single week of outflow, then reach one full pay period. You know it worked on the day you can pay a bill without checking when you next get paid.
This is educational information, not financial advice. For decisions about your own money, consult a licensed financial advisor.
Where this applies: written for readers in the United States. Pay schedules and account terms differ by employer and institution.
What a buffer is, and what it is not
A buffer is a timing tool. Its entire job is to absorb the mismatch between when bills arrive and when income arrives. It is not a reward, it is not savings, and it is not an emergency fund.
That last distinction matters more than any tip in this article:
| Buffer | Emergency fund | |
|---|---|---|
| Lives in | Your everyday checking account | A separate account, deliberately harder to reach |
| Job | Absorbs normal timing mismatch | Absorbs abnormal events |
| Used | Constantly, invisibly, every month | Rarely |
| Refilled | Automatically, by the next deposit | Deliberately, after an event |
| Success looks like | Never noticing it | Never touching it |
Guides routinely blend the two and then tell you to build "three to six months" of something. Those are different jobs. Sizing rules for the emergency fund are covered separately in how much an emergency fund should be; this page is only about the timing layer, and the timing layer is much smaller and much faster to build.
Stage one: cover your worst gap, not your monthly expenses
Most people quit because the target they were handed was "one month of expenses" and it looked like a year of work. So do not start there.
Start by finding the worst moment in your own month. Lay out every fixed outflow and every deposit on the same calendar, which is the exercise in how to make a bill calendar, and look for the point where the most money is committed before the next deposit lands.
Stage one target: the largest amount that must leave your account before the next deposit arrives.
For many people that is a single bill that falls two or three days early, the situation described in payday versus due date. Covering just that one gap removes the majority of the anxiety, because it removes the specific day that goes wrong.
This stage is usually one bill, not one month.
Stage two: cover your largest single week
Once the worst gap is covered, widen it to a week. Add up the committed outflows in your heaviest week of the month, which is normally the week rent or a mortgage payment lands, and make that the next target.
At this stage the buffer starts doing something new. It stops you from having to sequence payments around each other, and the balance in your app starts behaving predictably, because you are no longer riding the line described in available balance versus actual balance.
Stage three: one full pay period
Only now does "one paycheck ahead" become the target, and the number is not a month of expenses. It is one pay period's worth of committed outflow, which is a smaller number, and how much smaller depends on your pay schedule. Someone paid twice a month is targeting half the work of someone paid monthly, which is one of the practical consequences of biweekly versus semimonthly pay.
Where the money comes from
Four sources, in the order that actually works:
- A fixed transfer on payday. Small and automatic beats large and intentional. As Experian describes it in its own guidance on budget buffers, the mechanism that works is a small automatic transfer every paycheck rather than an occasional lump.
- The extra paycheck. If you are paid every two weeks, two months a year contain three paychecks. Those months are the single fastest way to fund a buffer, and the mechanics are in the three-paycheck month.
- A bill you removed or moved. Cancelling a subscription or moving a due date frees a fixed amount every month with no ongoing effort.
- Anything irregular that arrives. A refund, a rebate, a reimbursement. Money you were not planning your month around.
Notice what is not on that list: cutting daily spending by willpower. It works for some people and stalls for most, and it is not required for a buffer to exist.
The switchover day, which nobody describes
Here is the step almost every article omits, and it is the step where people get confused and quietly abandon the whole thing.
For as long as you are building, your buffer just looks like a slowly rising minimum balance in checking. Nothing changes about how you budget. You still plan the month using the money arriving in that month.
The switchover is a single decision, made on one day, when the buffer reaches one pay period. From that day forward, you plan the coming period using money that has already landed, rather than money that is scheduled to land. The paycheck arriving this Friday funds the period after this one.
Two things about that day, both of which surprise people:
- Your income does not increase. Nothing about the switchover creates money. You are the same distance from the same numbers. What changes is that your deadlines stop being live.
- Your balance will look high and it is not spendable. The buffer is the floor of your account, not a surplus above it. If you spend it, you have not lost savings, you have just quietly reset yourself to zero days of coverage. This is the most common way a completed buffer disappears.
A practical way to protect it: write the buffer amount somewhere you will see it, and treat that figure as the new zero. Some people move it to a separate account and transfer it back on the first of the month, which is safer against impulse and worse against a mistimed autopay. Both are defensible. The one that is not defensible is deciding you will simply remember.
What a buffer does not solve
Being honest about the limits.
A buffer fixes timing. It does not fix a shortfall. If your committed outflows genuinely exceed your income month after month, the buffer will fund the gap for a while and then be gone, and the underlying arithmetic will be exactly where it was. It buys time and calm, which is real, but it is not income.
It also does not protect you from a payment you forgot about. It makes that payment survivable rather than catastrophic.
And it takes longer than the internet implies. If your only funding source is a small automatic transfer, stage three is measured in months. That is normal, and stopping at stage one for six months is a legitimate outcome, not a failure.
FAQ
How much should a paycheck buffer be? Enough to cover the outflow committed before your next deposit. In stages: your worst single gap, then your heaviest week, then one full pay period. There is no universal dollar figure, because it depends entirely on your own bills and pay schedule.
Should the buffer sit in checking or savings? Checking is where it does its job, because the job is preventing a payment from failing. The trade-off is that money in checking is easier to spend by accident. If that risk is real for you, keeping it separate and transferring it in is a reasonable variation.
Is a paycheck buffer the same as an emergency fund? No. A buffer absorbs ordinary timing mismatch and is used every month. An emergency fund absorbs unexpected events and should mostly sit untouched. They are separate jobs and are usually held in separate places.
What if I cannot save anything at all right now? Then stage one is still available, because moving a due date or removing a recurring charge changes your timing without requiring you to save first. See how to change a bill due date.
Do I have to skip a month of spending to get ahead? No. That approach exists, and it works for people with irregular lump-sum income, but the incremental route reaches the same place without a month of strain. Neither is more correct.