
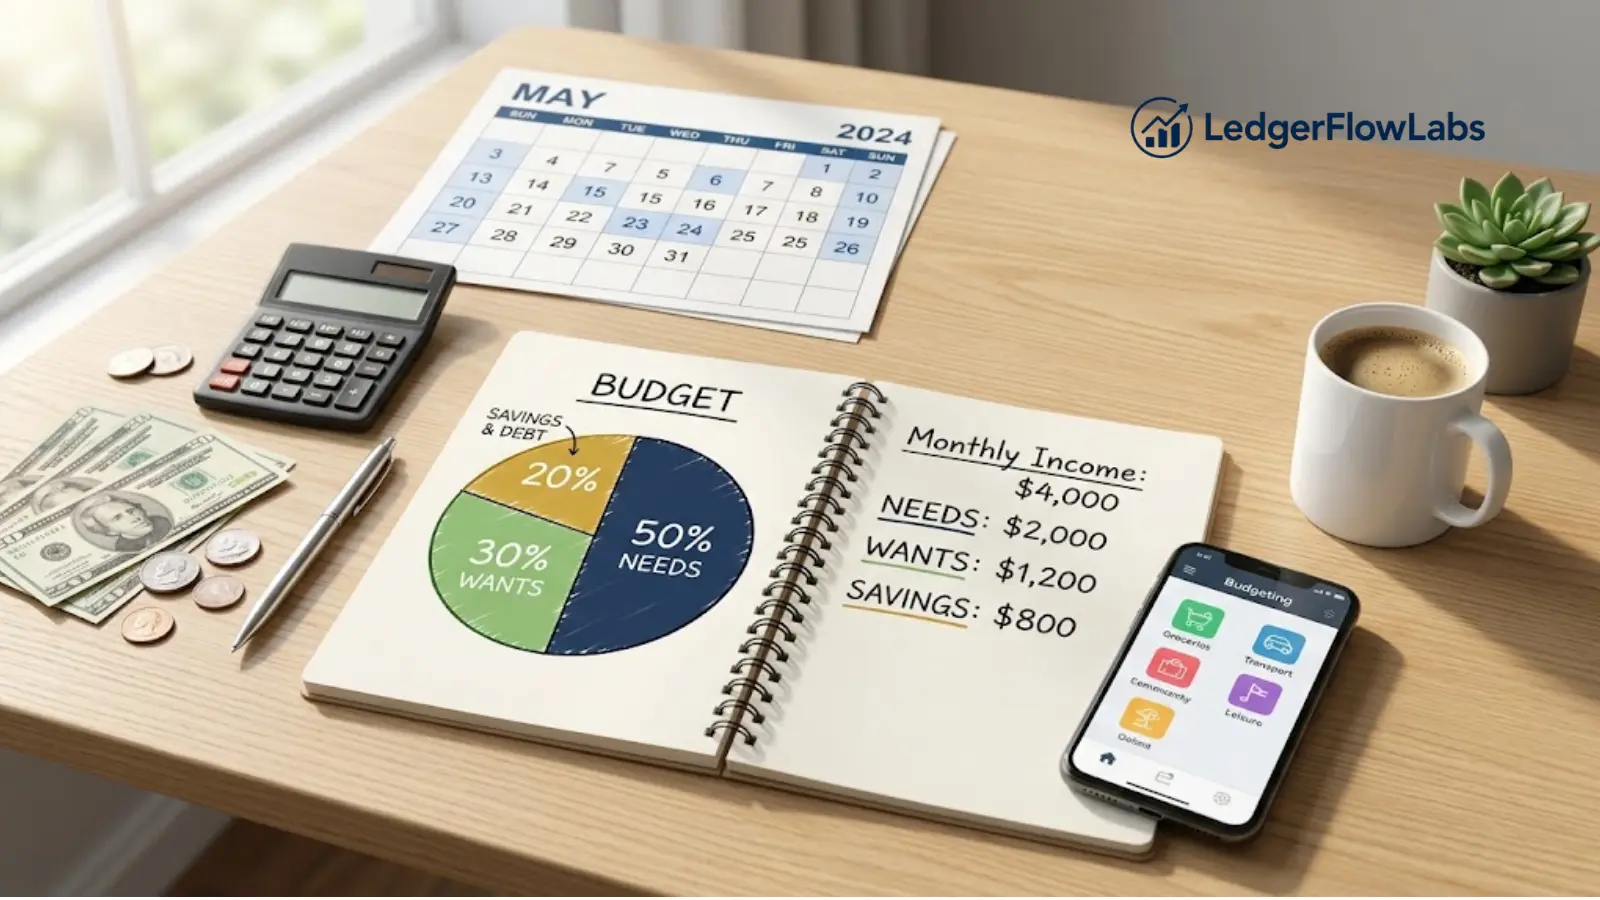
The 50/30/20 rule is a simple budgeting framework that splits your monthly take-home pay (your income after taxes) into three parts: 50 percent for needs, 30 percent for wants, and 20 percent for savings and debt payoff. Needs are the things you cannot skip, like rent and groceries. Wants are the things you enjoy but could live without. The final 20 percent goes toward your future, whether that is an emergency fund, retirement, or paying down debt faster. That is the whole rule. You do not need a spreadsheet or a finance degree to start, which is exactly why it works so well for beginners.
If you have ever finished a month wondering where your money went, this is one of the easiest ways to give it a plan. Below, I will walk through what each bucket means, where the rule came from, a full worked example using a made-up income, and the honest part most bank pages skip: when the 50/30/20 rule does not fit real life, and what to do instead.
This is educational information, not financial advice. For decisions about your own money, consult a licensed financial advisor.
What the 50/30/20 rule is, in one line each
The rule sorts every dollar of your take-home pay into three buckets. Here is the plain-English version of each.
- Needs (50 percent): the essentials you have to pay to keep your life running. As reported by Chase, this includes housing, utilities, groceries, insurance, transportation, and minimum debt payments.
- Wants (30 percent): the spending you choose but could survive without, such as dining out, streaming subscriptions, hobbies, travel, and upgrades you want but do not require.
- Savings and debt payoff (20 percent): money for your future self. As reported by Chase, this bucket covers building an emergency fund, contributing to retirement, and paying down debt beyond the minimum payment.
One important detail that trips up beginners: the percentages are based on your take-home pay, not your gross salary. Take-home pay is what actually lands in your account after taxes and payroll deductions. Budgeting off your gross number is a classic mistake, because you never see all of that money in the first place. Our full guide on whether to budget from gross or net income covers why, plus what to do if your paycheck amount is not the same every period.
Where the 50/30/20 rule comes from
The rule was popularized by Elizabeth Warren, then a Harvard Law professor and later a U.S. Senator, and her daughter Amelia Warren Tyagi, in their 2005 book "All Your Worth: The Ultimate Lifetime Money Plan." Warren and Tyagi had spent years studying why so many middle-class families felt broke even as their incomes rose. Their answer was that most people had no clear sense of what they could actually afford to spend. The 50/30/20 split was their fix: a rule simple enough to remember without a budgeting app or a background in finance.
It is worth being honest here. There is some debate about whether Warren invented the exact percentages, but she and Tyagi are widely credited with making the framework popular through that book. When you see banks and finance sites reference it today, this is the source they are pointing back to.
A worked example, dollar by dollar
Numbers make this concrete, so let us walk through one. Imagine someone takes home 3,000 dollars a month after taxes. To be clear, this is a hypothetical figure chosen for easy math, not a real person and not an average of anything. Here is how the 50/30/20 rule would divide it.
- Needs, 50 percent: 1,500 dollars. Rent, utilities, a phone plan, groceries, transportation to work, insurance, and any minimum loan or card payments all come out of this 1,500.
- Wants, 30 percent: 900 dollars. Eating out, a couple of streaming services, a gym membership, weekend plans, and the occasional new pair of shoes fit inside this 900.
- Savings and debt payoff, 20 percent: 600 dollars. This could be 300 dollars into an emergency fund and 300 dollars toward paying off a credit card faster, or all 600 into savings. The rule tells you the size of the bucket, not the exact split inside it.
The point of the example is not the specific numbers. It is the structure. Once you know your own take-home figure, you multiply it by 0.5, 0.3, and 0.2, and you instantly have three spending targets to aim at for the month.
What counts as a need vs a want (the tricky part)
This is where most people get stuck, and honestly, it is the part I found hardest when I started paying attention to my own spending. The line between a need and a want is blurry, and it is easy to quietly reclassify a want as a need to feel better about it.
A useful test: a need is something that has real consequences if you do not pay it. Miss your rent and you risk losing your home. Miss your electricity bill and the lights go off. A want is something that makes life more enjoyable but carries no such consequence if it disappears for a month.
The gray areas are real. Groceries are a need, but a weekly restaurant habit is a want, even though both are "food." A phone plan is a need in modern life, but the newest phone on an installment plan is closer to a want. Basic clothing is a need; a fifth pair of sneakers is not. You do not have to get this perfect. You just have to be honest with yourself, because the whole rule depends on that one classification skill. Our dedicated guide on needs versus wants walks through a two-question test and the specific categories where this line breaks down most, if you want to go deeper than this section.
The real strength of the rule: savings becomes a fixed line
Here is what makes 50/30/20 genuinely powerful, and it is the thing I wish I had understood earlier. In most people's budgets, savings is whatever happens to be left over at the end of the month. The problem is that "leftover" is almost always zero, because spending expands to fill whatever income is available.
The 50/30/20 rule flips that. It treats savings as a fixed 20 percent line, planned from the start, in the same category as your rent. You are not saving what is left. You are spending what is left after you save. That single reframe, sometimes called paying yourself first, is the difference between a budget that quietly builds a cushion and one that never does.
When the 50/30/20 rule does not fit (and what to do instead)
Now the honest section that the big brand pages tend to skip. The 50/30/20 rule is a helpful target, not a law of nature, and there are real situations where the percentages simply do not work.
When your needs are already more than 50 percent. If you live in a high-cost-of-living area, or your income is low, rent and essentials alone can eat well past half your take-home pay. That does not mean you are failing at budgeting. It means the standard split is unrealistic for your situation right now. A better move is to treat 50/30/20 as a direction to grow toward: keep needs as controlled as you can, shrink wants temporarily, and save whatever percentage is actually possible, even if it is 5 percent rather than 20. A small, consistent savings habit still beats none.
When the percentages feel too loose. Some people find that "spend up to 900 on wants" is not enough structure, and the money still slips away inside that bucket. If you want tighter control where every single dollar has a defined job, a method called zero-based budgeting fits better. I break that approach down in a separate guide on zero-based budgeting for beginners, which is the higher-control alternative to the loose percentages here.
When your income is irregular. If you are paid on commission, freelance, or work variable hours, a fixed monthly percentage is hard to pin down. In that case, budgeting off your lower-earning months and treating the percentages as an average across the year works better than forcing the split onto a single unpredictable paycheck.
The takeaway: if the rule fits, use it. If it does not, adjust the percentages to your reality or choose a method built for more control. The goal is a plan you will actually keep, not a perfect ratio you abandon in week two.
How to start using the 50/30/20 rule this month
You can set this up in one sitting. Here is the short path.
- Find your monthly take-home pay, the amount that actually hits your account after taxes.
- Multiply it by 0.5, 0.3, and 0.2 to get your three targets.
- Look at last month's spending and sort it into needs, wants, and savings, so you can see where you stand today.
- Adjust for one month, then check in and correct. Budgeting is a loop, not a one-time setup.
If you want the full walkthrough with each step spelled out, follow my guide on how to build your first monthly budget step by step. And if you are still deciding whether 50/30/20 is even the right method for you, start with the overview in budgeting for beginners, which compares the main approaches side by side.
FAQ
Does the 20 percent include debt payments? Your minimum required debt payments are usually counted as a need, inside the 50 percent bucket, because you have to make them. Extra payments to clear debt faster, beyond the minimum, typically sit in the 20 percent savings and payoff bucket. As reported by Chase, paying down debt above the minimum belongs with your savings goals. How you split that bucket is up to you.
What if my needs are more than 50 percent of my income? This is common, especially on a lower income or in an expensive area. Treat 50/30/20 as a target to grow toward, not a rule you have failed. Keep your needs as lean as you can, trim wants for now, and save whatever percentage is realistic, even a small one. The habit matters more than hitting exactly 20 percent right away.
Is the 50/30/20 rule good for beginners? Yes, it is one of the best starting frameworks precisely because it is so simple. The trade-off is that it is loose. It tells you how much to spend on wants but not on what, so some people overspend inside the 30 percent bucket. If you want tighter control, a zero-based approach gives you more structure.
Should I use gross or take-home pay for the 50/30/20 rule? Use your take-home pay, meaning your income after taxes and payroll deductions. Budgeting off your gross salary is a frequent beginner mistake, because it includes money you never actually receive, which throws all three buckets off.
Is 50/30/20 better than zero-based budgeting? Neither is universally better; they suit different people. The 50/30/20 rule wins on simplicity and low effort. Zero-based budgeting wins on control and precision, since every dollar gets assigned a job. Pick based on how much structure you personally want to maintain each month.
Reminder: this article explains general budgeting principles and is not personalized financial advice. For guidance on your own situation, consult a licensed financial advisor.