
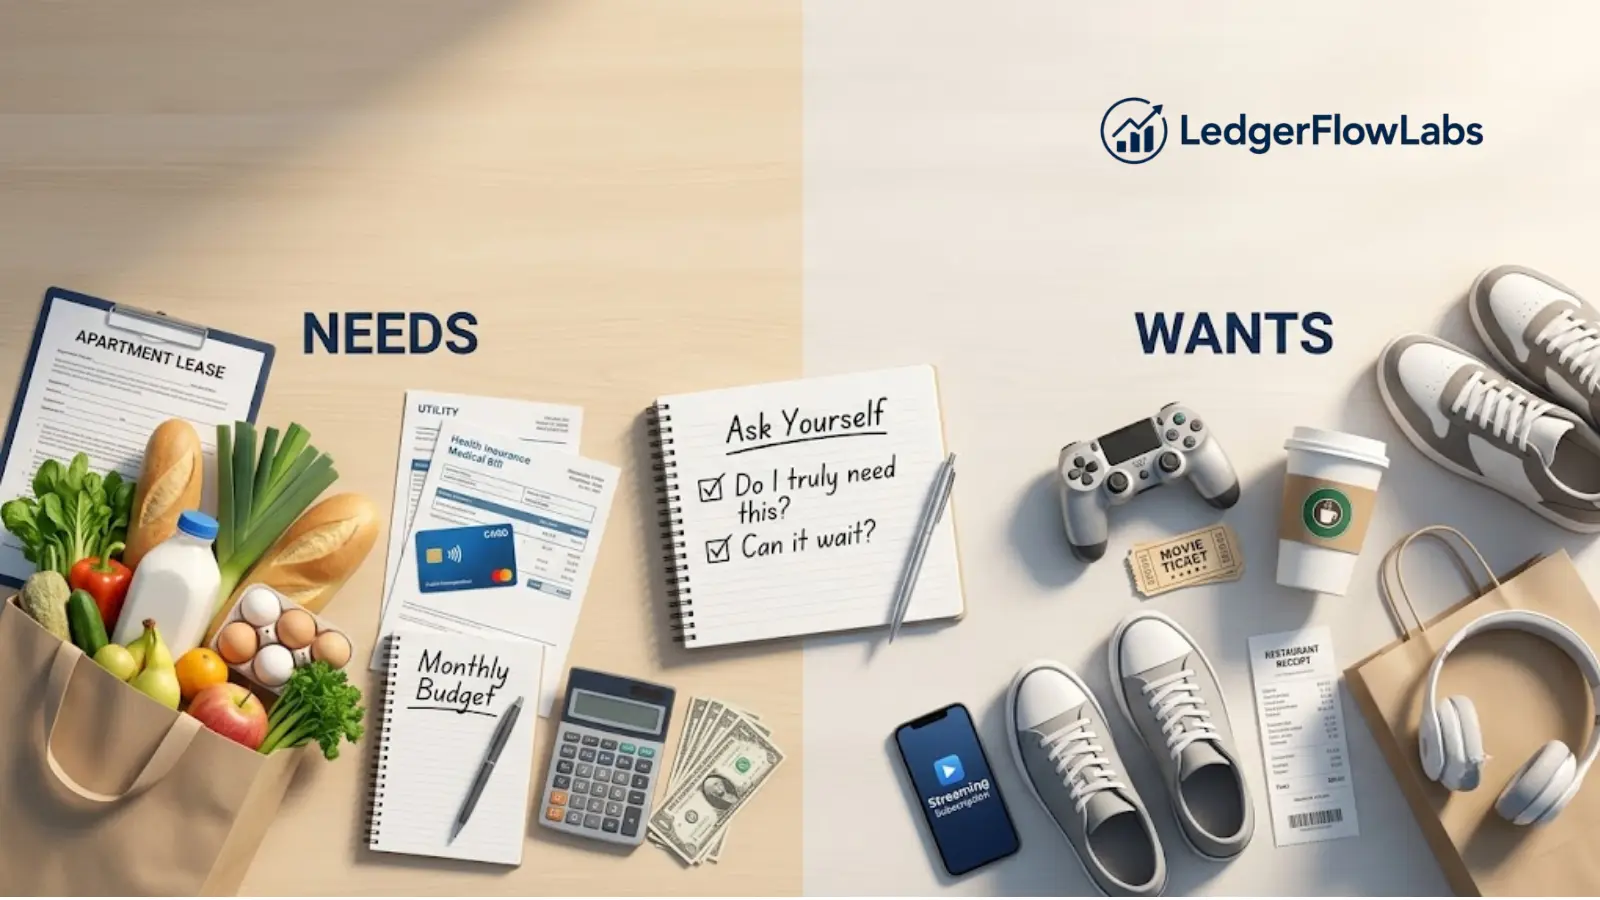
Telling a need from a want comes down to two honest questions, not a list someone else wrote for you: does the desire to have it fade with time, and would skipping it cause a real, functional consequence? A need is something that keeps growing more urgent the longer you put it off (rent, a medical bill, groceries), and something that causes a genuine problem if you do not pay it. A want is something you can feel the pull of today and barely remember by next week, and something that costs you nothing but disappointment if it disappears. The categories are not universal. They depend on your actual life, your actual job, and your actual obligations, which is exactly why a generic list never quite fits.
This is educational information, not financial advice. For decisions about your own money, consult a licensed financial advisor.
A note on the numbers: the dollar figures later in this guide are illustrative examples chosen to make the method concrete. They are not typical US household costs, and your own categories will depend on your actual job, lease, and obligations.
What counts as a need, what counts as a want
A need is an expense that keeps your life functioning: housing, utilities, groceries, basic transportation to work or school, insurance, and the minimum payments on any debt you owe. As reported by SoFi, needs are the purchases required to stay safe, healthy, employed, and functional, not simply to survive.
A want is an expense that makes life more enjoyable but carries no functional consequence if it disappears: dining out, streaming subscriptions, a vacation, the newest version of something you already own that still works. As reported by Experian, wants are nonessential purchases that enhance quality of life rather than sustain it.
That definition sounds simple until you apply it to your own spending, which is where nearly everyone gets stuck.
The honest test: two questions, not a list
Skip the list. Lists are always someone else's life. Instead, ask two questions about the specific expense in front of you.
Question one: does wanting it grow or fade with time? As reported by SmartAsset, one useful signal is that the desire to obtain a genuine need tends to intensify the longer it goes unmet, while the pull of a want tends to weaken the longer you sit with it. If you can go a month without something and barely think about it, that is a want telling on itself. If putting it off keeps getting more urgent and more uncomfortable, that is a need.
Question two: is there a real, functional consequence if you skip it? Not an emotional consequence. A functional one. Missing rent risks your housing. Missing a phone bill, if your job requires you to be reachable, risks your ability to work. Missing a streaming payment risks nothing except boredom for an evening. As reported by U.S. News & World Report, the clearest test is to ask what actually happens, in practical terms, if the payment simply does not happen this month.
Run both questions on the same expense and the two answers usually agree. When they do not, question two wins, because functional consequence is the harder fact.
Reclassification creep: how a want quietly becomes "a need"
Here is the part almost nobody names directly, and it is the reason the same list of needs and wants does not stay accurate for very long. Wants do not stay labeled as wants. They drift.
It starts small. A takeout order that was originally a "sometimes, when I am too tired to cook" treat becomes a twice-a-week habit. Somewhere in that drift, the language in your own head changes from "I want this" to "I need this, I have had a long week." Nothing about the expense changed. The label did. That relabeling is what lets a want survive a budget review month after month while a person is still telling themselves, honestly, that their needs are eating their whole paycheck.
The fix is not guilt. It is a periodic re-ask. Once every month or two, take your recurring "needs" and run the two-question test on them again, as if you had never labeled them before. If a "need" fails the functional-consequence test on a fresh look, it was reclassified at some point without you deciding it on purpose. That does not mean you have to cut it. It means you get to make the choice again, deliberately, instead of by default.
The five categories where the honesty test breaks down most
Some expenses are easy: nobody argues that rent is a need or that a weekend trip is a want. The argument always happens in the same five places. Here is each one, worked through with both questions.
Subscriptions. Almost always a want. The exception is a subscription that is a genuine, required tool for your paid work, and even then, only the tier your job actually requires. A streaming bundle, a gaming subscription, or an extra cloud storage plan you are not using for anything essential fails both tests: the desire fades fast when you are not using it, and skipping it has no functional consequence.
Phone and device upgrades. A working phone that lets you be reachable for work and daily life is close to a need in most modern jobs. The newest model of that same phone, bought while the old one still works, is a want. The test separates the device from the upgrade cycle: having a phone at all can be a need; wanting this year's phone specifically almost never is.
Dining out. Food is a need. The specific choice to buy it prepared, repeatedly, at a markup over cooking it yourself, is a want, even though both fall under "food." The consequence test makes this one easy: skipping a restaurant meal has no functional effect on your life. Skipping groceries entirely would.
Clothing. Basic clothing that lets you show up for work and daily life is a need. A closet's worth of options beyond that is a want, including clothing you buy because it is on sale rather than because you need it. Someone whose job genuinely requires specific attire (a uniform, safety gear, professional dress a role mandates) has a real need where someone else has a preference. This is the clearest case of the same expense category being a need for one person and a want for another, depending on the actual job.
A car versus a car tier. Transportation to work, when no reasonable alternative exists, can be a genuine need. The specific vehicle, its age, its features, and its monthly payment size are a separate question entirely, and that part is almost always partly want. Needing a way to get to work does not mean needing this particular car at this particular price.
Why this classification matters more than the method you pick
Every popular budgeting method leans on this exact skill. The 50/30/20 rule asks you to split your take-home pay into needs, wants, and savings, and the whole framework collapses if your needs bucket is quietly stuffed with wants you have relabeled. Zero-based budgeting asks you to give every dollar a job, and a dollar assigned to a fake "need" is a dollar you never questioned. This is exactly why our overview of budgeting for beginners treats method choice as secondary: the method organizes your money, but this classification decides whether the numbers going into it are honest in the first place. It is also, as our guide to why budgets fail covers directly, one of the most common ways a first budget quietly goes wrong from day one.
What to do with a want you are not ready to cut
Being honest that something is a want does not mean you have to give it up. It means you stop hiding it inside your needs column, where it distorts every decision after it. Move it into your wants total, on purpose, and decide with open eyes whether it still fits inside what you can afford. Plenty of wants earn their place in a budget. The problem was never wanting things. The problem is not knowing which numbers are which.
This classification gets genuinely harder, not easier, once two people share a budget, because each partner brings their own honest sense of what feels essential. Our guide to budgeting as a couple covers how to have that specific conversation without it turning into a fight about who is right.
FAQ
Is a car a need or a want?
Getting to work, when there is no reasonable alternative, can be a genuine need. The specific vehicle you drive, and how much car you buy beyond basic reliable transportation, is largely a want. Separate "do I need transportation" from "do I need this particular car."
Are subscriptions ever a need?
Rarely, and only when a subscription is a required tool for your paid work, at the tier your job actually requires. Entertainment subscriptions, even ones you use often, are wants under both the fading-desire test and the functional-consequence test.
What if my needs genuinely take up more than half my income?
That happens, especially in high-cost areas or on a lower income, and it is not a personal failure. It is worth re-running the two-question test on your "needs" column first, since reclassification creep is common, and then working from your real totals rather than a percentage that assumes otherwise.
How often should I redo this classification?
Every month or two is enough to catch drift before it becomes invisible. Recurring expenses are the ones most likely to have quietly changed labels since the last time you looked honestly at them.
Do minimum debt payments count as a need?
Yes. The required minimum on a credit card, auto loan, or student loan has a real consequence if you skip it: a late fee, and after enough time a delinquency reported to the credit bureaus. That puts the minimum firmly in the needs column. Anything you pay above the minimum is a savings and payoff decision, not a need, which is why the two are budgeted separately.
Reminder: this article explains general classification principles, not personalized advice. For decisions about your own money, consult a licensed financial advisor.