
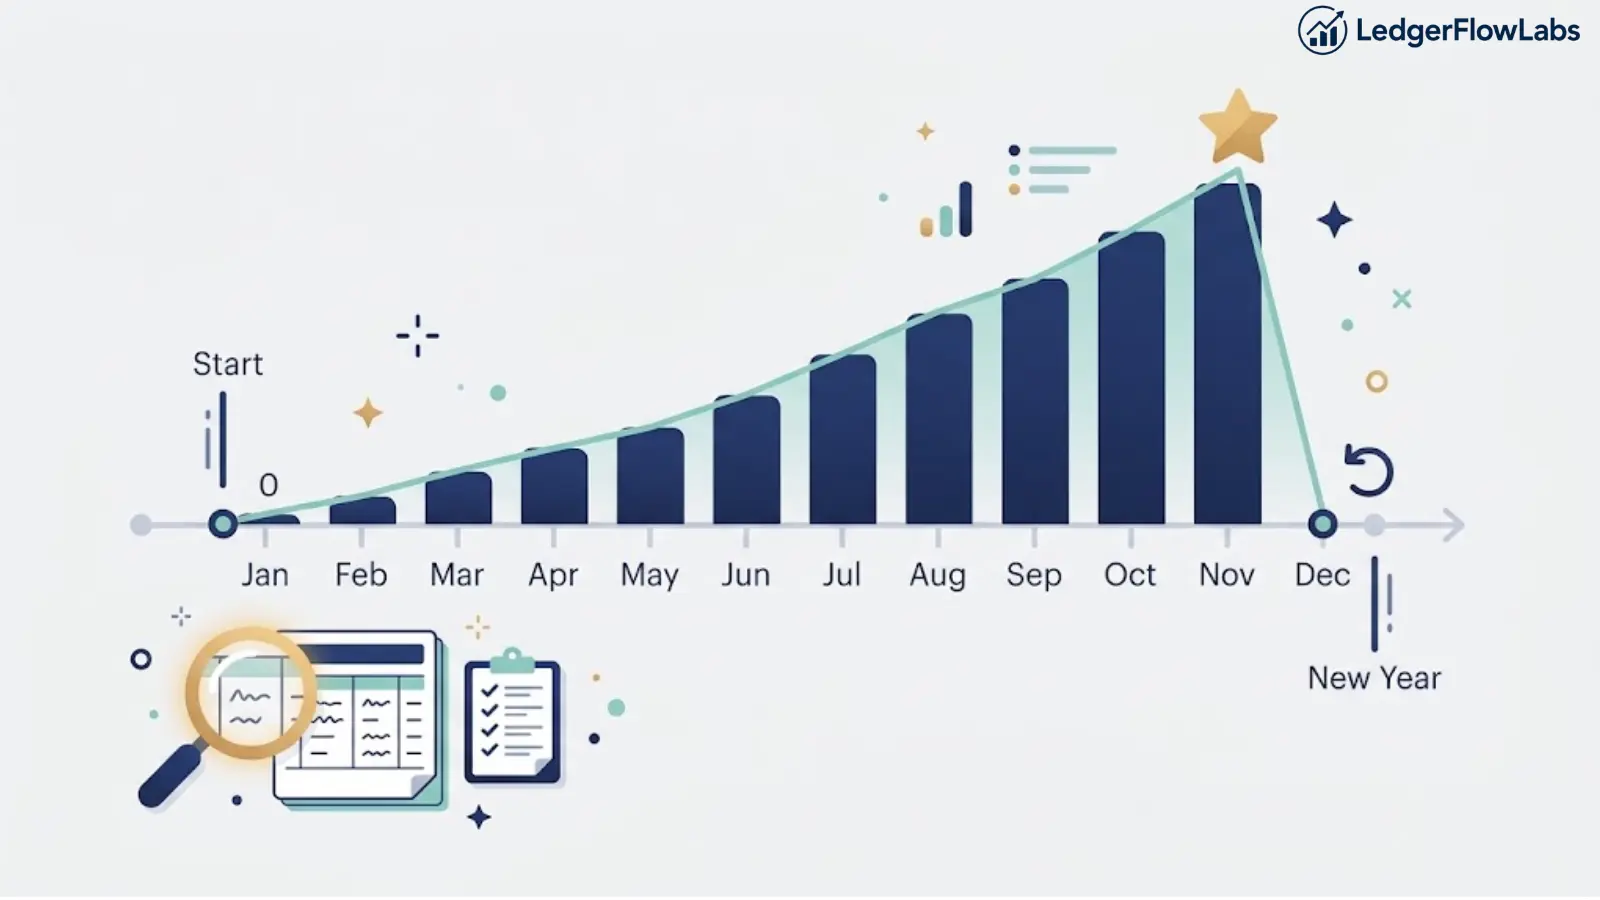
Short answer: YTD stands for year to date. It is the running total of a line since January 1 of the current calendar year, printed beside the figure for the current pay period. It follows the calendar year, not your hire date or your employer's fiscal year, and it resets to zero every January whether you started in February or have been there a decade. It is worth checking because it is the closest thing you have to a draft of your Form W-2, and because it makes several errors visible months before filing season would.
This is educational information, not tax advice and not financial advice. It explains what the column is and what it can show you. It does not tell you what to withhold, what to claim, or whether your own totals are correct.
Where this applies: the United States, on the pay stub of an employee who receives a Form W-2. The year to date idea exists on payroll documents in many countries, but the forms, the tax year and the line names below are US ones. Several countries run a tax year that does not start in January, so a reader elsewhere should not assume the reset date described here.
What is in the column
Most stubs print two figures for every line. The first is this pay period. The second, usually headed YTD, is the total for that line since the start of the calendar year.
You will typically find a running total for each of these:
- YTD gross: everything you have earned this year before deductions, including overtime, bonuses and paid leave.
- YTD taxes: what has been withheld so far for federal income tax, Social Security, Medicare, and state or local tax where they apply.
- YTD deductions: the accumulated total of each benefit line, such as a health premium or a retirement contribution, often itemized rather than lumped.
- YTD net: the total that has actually reached you this year.
Some employers also print YTD employer contributions, which are what the company paid on your behalf. Those are information rather than money taken from you.
One boundary worth stating. The YTD column covers this employer only. If you changed jobs in March, your current stub knows nothing about January and February, and your total earnings for the year are spread across two sets of records.
Check one: does the running total actually run?
The quickest use of the column takes about a minute and needs two stubs.
Take last period's YTD figure for any line. Add this period's figure for the same line. The result should equal this period's YTD.
When it does not, something has been added, missed or reversed. A duplicated period, a skipped one, a correction applied without explanation, or a benefit backdated to an earlier date all show up here. Finding that in April is an ordinary conversation with payroll. Finding it in February of the following year, when the numbers have already become a W-2, is a much longer one.
Check two: your real average per period
A single check is a poor description of your income. It can be inflated by overtime, deflated by an unpaid day, or distorted by a benefit that started mid period.
The YTD column fixes that, because dividing YTD gross by the number of pay periods completed so far gives you your true average earnings per period this year. The same division on YTD net gives the figure your household actually receives on an average payday.
That average is the number worth planning around when your pay moves, and it is far more reliable than the check you happen to be holding. It is the same logic as budgeting on irregular income, where the goal is a defensible baseline rather than a best case. If you are unsure how many periods should have passed by now, that depends on your pay frequency, which is set out in weekly, biweekly and semimonthly pay, and it is also why some months contain an extra deposit, as in a three paycheck month.
Check three: the stub is a draft of your W-2
At the end of the year your employer issues a Form W-2, and the figures on it are built from the same running totals you have been watching all year.
This is why the last stub of the year is worth keeping somewhere you can find it. When the W-2 arrives, the two documents can be compared.
Expect them to disagree in a specific way, and know why. The wage boxes on a W-2 are not simply your YTD gross, because pre-tax deductions are excluded from some of them and not from others. Traditional retirement contributions, for example, are left out of the federal wages figure while still counting as Social Security and Medicare wages. A stub and a W-2 that differ for that reason are behaving normally.
What you are looking for is a difference the pre-tax rules do not explain. That is a question for your employer's payroll department, and it is far easier to resolve in January than after a return has been filed.
Check four: the things that are tracked annually, not per period
Some payroll amounts are governed by annual figures rather than by what happens in a single period. Retirement plan contributions have annual limits. Social Security withholding stops once annual earnings reach a wage base. Certain additional taxes begin only above an annual earnings figure.
This page prints none of those numbers, deliberately. They are set each year, they change, and a figure quoted here would be wrong for somebody reading it in a later year. The IRS and the Social Security Administration publish the current ones, and your plan administrator can tell you what applies to your plan.
What the YTD column gives you is the input to those rules: your progress through the year. It is the reason the column matters most in two situations.
If you changed employers mid year, each employer tracks its own YTD from your start date with them and does not see the other, while several annual limits apply to you as a person across the whole year. Whether that produces an issue, and what to do about it, is a question for a tax professional or the IRS.
If your pay is uneven, a large bonus or a heavy overtime stretch moves you through the year's annual figures faster than a steady salary would, which can change your take-home pay later in the year with no raise involved.
Check five: proof of income, without waiting for a form
A recent stub with a YTD column is often accepted as evidence of current income, and it has one advantage over a W-2: it describes this year rather than last year. Lenders, landlords and benefit applications commonly ask for recent stubs for exactly that reason.
Keeping them is worth the small effort. Payroll portals do not always hold documents indefinitely, particularly after you leave a job, and a stub you cannot retrieve is a record you do not have. Your own copies also make the year to year comparison possible: looking at the same running total at the same point in two different years shows the direction your income is moving, which is the annual version of reading your own cash flow across three months.
What the YTD column cannot tell you
It cannot tell you whether the right amount of tax is being withheld for your situation. It is a record of what has happened, not a verdict on whether it should have.
It cannot tell you your total income for the year if you have more than one employer, or income that does not arrive through payroll.
And it cannot tell you what you will owe or be refunded when you file. Withholding is a running estimate that is settled on a tax return, and the settlement depends on facts that never appear on a pay stub.
FAQ
What does YTD mean on a pay stub? Year to date: the total for that line since January 1 of the current calendar year, printed next to the amount for the current pay period.
Does YTD start from my hire date? No. It follows the calendar year, so it resets on January 1 regardless of when you started. If you joined in June, your first year's YTD only covers June onward and still resets the following January.
Why does my YTD gross not match my W-2? Because some wage boxes on a W-2 exclude pre-tax deductions and others do not. A difference the pre-tax rules explain is normal. A difference they do not explain is a question for payroll.
Can I use my pay stub as proof of income? Often yes, and a recent stub with a YTD figure describes the current year rather than the last one. Whether a particular lender or agency accepts it is their decision.
What if my YTD totals look wrong? Compare last period's YTD, this period's amount and this period's YTD, since they should reconcile. If they do not, your employer's payroll department holds the records that explain it.
Sources: Internal Revenue Service, for Form W-2 and Form W-4 and for the treatment of pre-tax contributions in the wage boxes of a W-2, named as documents rather than quoted, read 2026-09-07. Annual limits, wage bases and thresholds are deliberately not reproduced on this page. They are set each year and are published by the IRS and the Social Security Administration.