
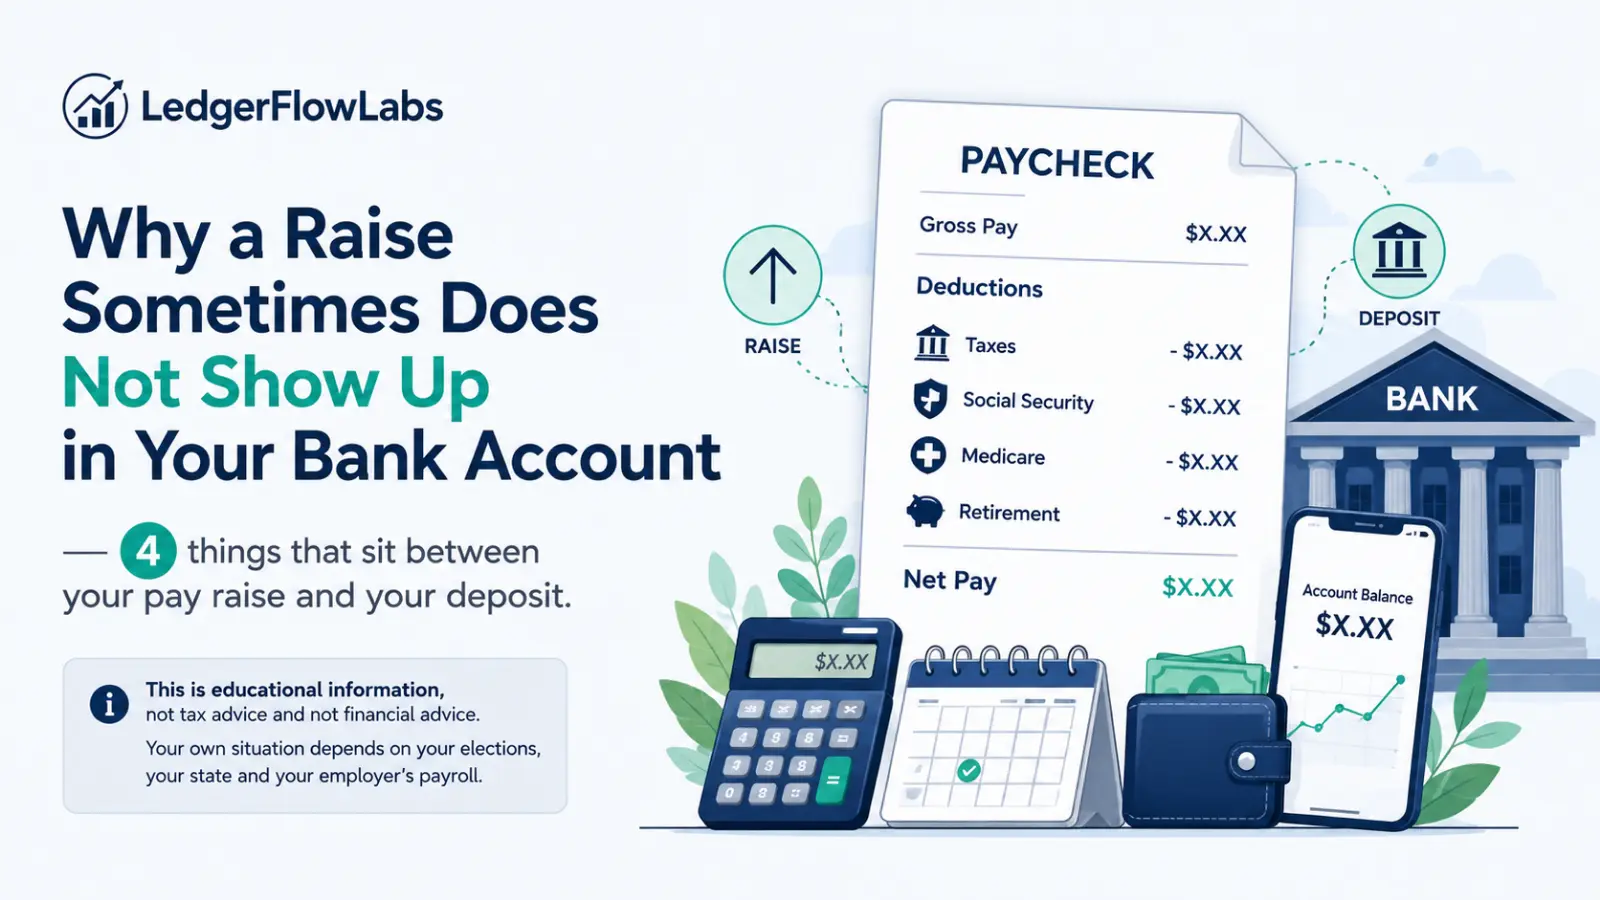
Short answer: the raise is a change to your gross pay and your deposit is net pay, and four different things sit between the two. Three of them scale with your pay, so they grow when it does. In the United States the two you can look up are Social Security and Medicare withholding: the IRS states that "the current tax rate for Social Security is 6.2% for the employee" and "the current rate for Medicare is 1.45% for the employee" (IRS Tax Topic 751, last updated January 20, 2026). Percentage-based deductions such as a retirement contribution do the same thing. Add income tax withholding, which is not a flat percentage, and a mid-period effective date, and a raise that looks like a real number on a letter can arrive as a much smaller change in the account.
Where this applies: the United States. Payroll deductions, tax withholding and social insurance work differently in every country.
This is educational information, not tax advice and not financial advice. Your own situation depends on your elections, your state and your employer's payroll.
Gross, net, and the four things in between
Gross pay is the number in the raise letter.
Net pay is what lands.
Between them, in the order they usually appear on a stub:
1. Pre-tax deductions. Retirement contributions, health premiums, and similar. Some of these are a percentage of pay, and a percentage of a bigger number is a bigger deduction. If you contribute a percentage to a retirement plan, part of your raise went straight into it, which is not money lost but is money that did not arrive in the account.
2. Federal income tax withholding. Not a flat rate, and not the same as your tax rate. It is calculated by your employer's payroll from the information on your Form W-4, and it responds to a change in pay.
3. Social Security and Medicare. The IRS publishes the employee rates: 6.2% for Social Security and 1.45% for Medicare. Both are percentages of pay, so both grow with a raise. The IRS also states that for earnings in 2026 the Social Security wage base limit is $184,500, and that employers withhold an Additional Medicare tax of 0.9% on wages paid to an individual in excess of $200,000 in a calendar year.
4. State and local withholding, and post-tax deductions. These vary by where you work and by what you have elected.
Three of those four scale with pay. Which is why a raise of a given size never arrives as that size, and why "my take-home barely moved" is usually arithmetic rather than an error.
Where to look on your own stub
This is the part worth doing, because it turns a vague disappointment into a number.
Find a stub from before the raise and a stub from after it. Same pay period length, ideally.
Compare the gross figures. Confirm the raise actually applied and that it applied for the whole period. Which brings us to the commonest single explanation, below.
Line the deductions up side by side. Every line that went up is a line that is taking part of the raise. Add the increases. Gross increase minus the sum of the deduction increases is your net increase, and it should match the change in the deposit.
If it does not match, the difference is worth taking to your payroll department rather than assuming. Stubs are documents you are entitled to read and to ask about.
The commonest explanation, and it is temporary
The raise did not apply for the whole pay period.
If your raise took effect mid-period, that period contains some hours at the old rate and some at the new one. The first check after a raise is very often a blend, and the second one is the real one.
Check the date the raise took effect against the start date of the pay period. If the first falls inside the second, wait for the next full period before drawing conclusions.
There is a related timing question people run into at the same moment: pay date versus pay period. The pay date is when the money arrives; the pay period is the work it covers, and they are always offset. How that interacts with the rest of your month is covered in biweekly vs semimonthly pay.
The withholding change nobody expects
Federal income tax withholding is calculated per pay period, and payroll systems generally compute it as though the current period's pay continued for the whole year.
One practical consequence: a one-off payment in a period, a bonus, backdated pay, or an unusually large check, can be withheld against at a higher effective rate than your normal pay is, because the calculation treats that period as typical.
A second one: a raise moves your annualized figure, so the withholding on every subsequent period changes too, not just on the first one.
Neither of these means you have paid the wrong amount of tax overall. Withholding is an estimate that is reconciled when you file. What it means is that the change in your deposit is not a straight percentage of the change in your gross, and it is not supposed to be.
If your withholding looks wrong to you, the document that controls it is your Form W-4, and the IRS publishes a withholding estimator. Whether to change your W-4 is your decision and not one this page will make for you.
The wage base, which matters at one specific point in the year
The IRS states that for earnings in 2026 the Social Security wage base limit is $184,500. Above that, Social Security withholding stops for the year while Medicare continues.
Two consequences worth knowing rather than acting on. For a household that reaches the limit, take-home pay rises later in the year without any raise at all and then falls again in January. And a raise that pushes earnings across the limit produces an uneven pattern across the year.
Both are arithmetic rather than errors, and both are the kind of thing that shows up clearly if you are already reading three months of your own deposits side by side rather than looking at one month at a time.
Why this matters beyond disappointment
Because plans get built on the gross number.
A household that raises its committed outflow by the amount of the raise letter has increased its commitments by more than its income actually rose. If a new commitment starts in the same month, that is exactly the situation that produces a structurally short week, which we take apart in why you run out of money before payday.
The safe move is to wait for two full pay periods at the new rate, take the actual deposit figure, and plan on that. If you are rebuilding a budget around a new income, gross or net: which income number to budget from is the page for it, and the answer there is not ambiguous.
FAQ
Why did my raise barely change my take-home pay? Because three of the four things between gross and net scale with pay. The IRS publishes the employee rates for Social Security at 6.2% and Medicare at 1.45%; percentage-based deductions such as a retirement contribution behave the same way; and income tax withholding recalculates on the higher figure.
Did I get moved into a higher tax bracket and lose money? Marginal rates apply to the income above a threshold, not to all of it, so more gross pay does not produce less net pay through brackets alone. If your net went down, look for a deduction that changed, a benefits election, or a period that was not a full period at the new rate.
How much is withheld for Social Security and Medicare? The IRS states the employee rates as 6.2% for Social Security and 1.45% for Medicare, with a Social Security wage base limit of $184,500 for earnings in 2026, and an Additional Medicare tax of 0.9% withheld on wages above $200,000 in a calendar year.
My first check after the raise looked wrong. Should I worry? Check whether the effective date of the raise fell inside the pay period. If it did, that check is a blend of the old and new rates and the next full period is the one to judge by.
Why was my bonus withheld at such a high rate? Payroll withholding is generally calculated as though the current period's pay continued all year, so an unusually large period is withheld against as though it were typical. It is an estimate reconciled when you file, not a final tax.
Where do I check all this? Your pay stub, comparing one from before the raise with one from after. Every deduction line that increased is a line that took part of the raise. If the arithmetic does not close, ask payroll.
Sources: Internal Revenue Service, Tax Topic 751, "Social Security and Medicare withholding rates", read 2026-08-28, page last updated January 20, 2026, for the 6.2% Social Security and 1.45% Medicare employee rates, the $184,500 Social Security wage base limit for earnings in 2026, and the 0.9% Additional Medicare tax withheld on wages above $200,000 in a calendar year. No other figure appears on this page. No state or local rate is given, because they vary and none was verified for this article.