
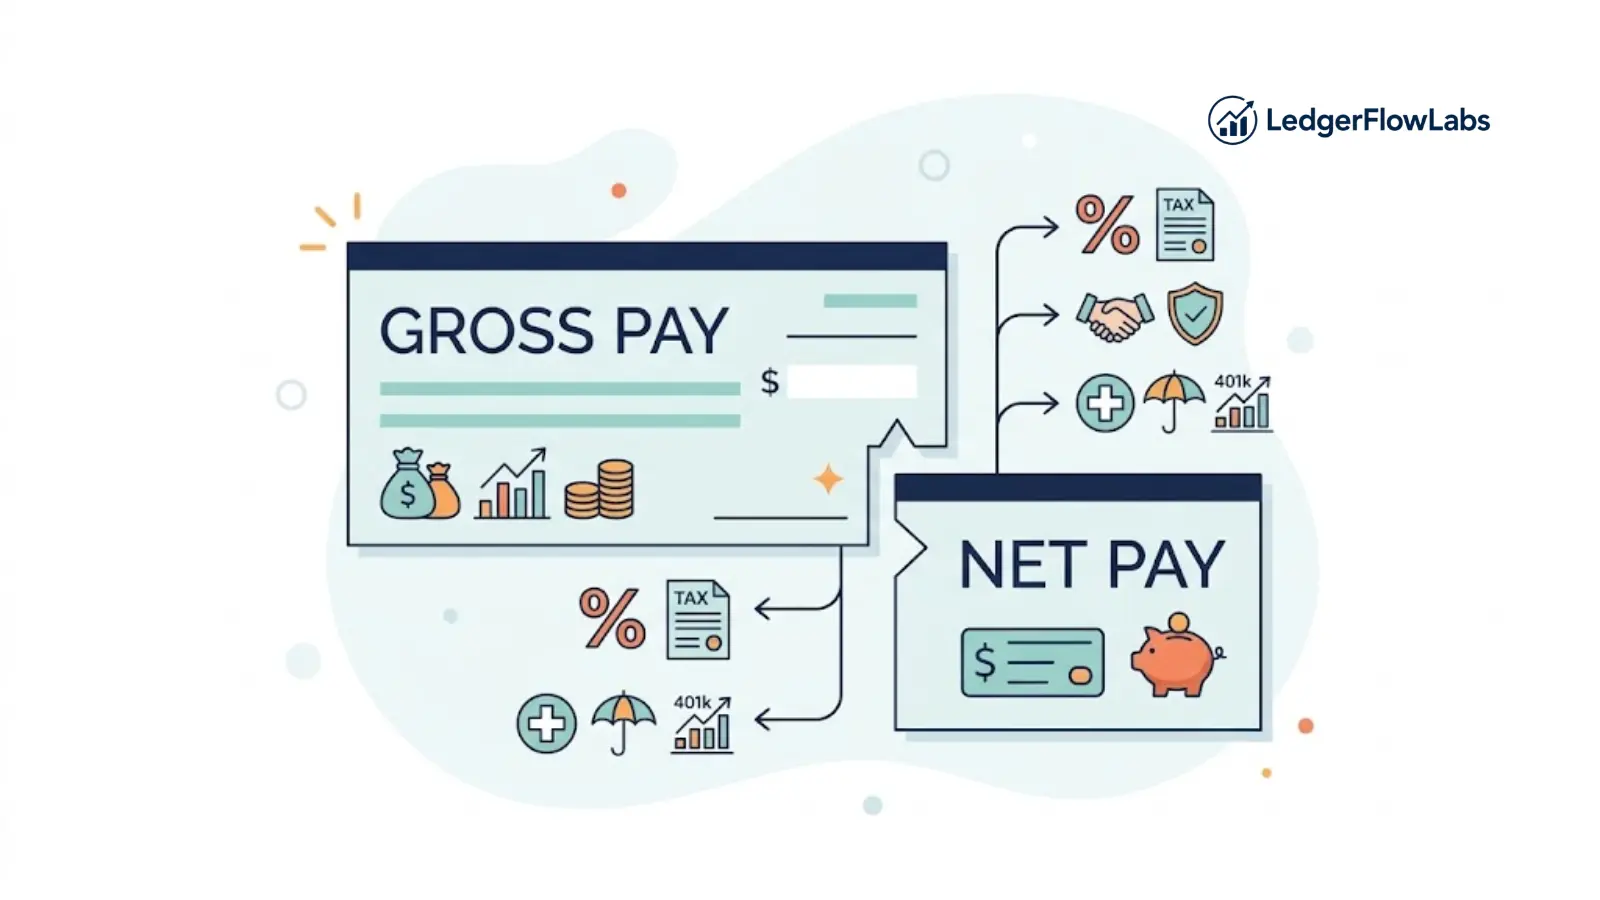
Short answer: gross pay is what you earned this period. Net pay is what reaches your account. The difference does not go to one place, it goes to four or five, and they are not the same kind of thing. Some of it is a prepayment on a tax bill that gets reconciled when you file. Some of it is a contribution to a social insurance system. Some of it is still your money, sitting in an account with your name on it. Some of it bought you something, such as health coverage. Your pay stub lists every one of those destinations by name, which is why the gap is knowable rather than mysterious.
This is educational information, not tax advice and not financial advice. It explains what happens to the difference. It does not tell you what to elect, what to withhold, or whether your own amounts are correct.
Where this applies: the United States, and the pay stub of an employee who receives a Form W-2. The categories below are the ones a US payroll system produces. Every country splits the gap differently. A Canadian reader will see Canada Pension Plan and Employment Insurance deductions instead of the US ones, and different forms behind them, and none of that is described here.
The two numbers, once
Gross pay is total earnings for the pay period before anything is taken out: base wages or salary, plus overtime, bonus, commission, shift differential and paid leave for that period.
Net pay is what is left after every withholding and deduction. It is the number that matches your deposit, and it is the only one of the two you can actually spend.
Everything else on this page is about the space between them.
Where the difference goes, by destination
Most explanations of gross and net stop at the formula. The formula is not the interesting part. The destinations are, because they behave completely differently once the money leaves your check.
| The line on your stub | Where the money goes | Is it still yours? |
|---|---|---|
| Federal income tax withholding | To the Internal Revenue Service, as a prepayment against this year's tax bill | It is a deposit, not a final charge. It is settled up when you file |
| Social Security and Medicare (often shown as FICA, OASDI, Med) | To the federal social insurance programs, collected by the IRS | No. It is a contribution, not a savings balance, and it is not refunded at filing |
| State income tax, and sometimes a city or local tax | To your state or local revenue agency, where one exists | Also a prepayment, reconciled on that state's return |
| Retirement plan contribution, such as a 401(k) or 403(b) | Into a retirement account in your name | Yes. It left your paycheck and did not leave your ownership |
| Health, dental or vision premium | To an insurer, for coverage you are receiving | No, but it bought a specific thing |
| HSA or FSA contribution | Into an account in your name for eligible expenses | Yes, with rules attached about what it can be spent on and when |
| Garnishment or court-ordered support | To a third party, under a legal order | No, though it reduced a debt or obligation you owed |
| Union dues, life or disability premiums, charitable payroll deduction | To the named organization or insurer | No, but each one is something you or an agreement signed up for |
Sorted this way, a stub reads differently. Two lines that look identical, both reducing your take-home pay by the same amount, can be doing opposite things. One is buying coverage you consume this month. The other is moving money from your checking account to your retirement account without changing how much you own.
The part that surprises people: not all of the gap is spent
There is a habit of treating the whole gross to net difference as money lost to taxes. It is worth separating, because the shares vary enormously between two people on identical salaries.
Money that is genuinely gone: the social insurance contributions and any premium or fee that paid for something already delivered.
Money that is still yours: retirement contributions, health savings balances, and anything else that landed in an account bearing your name.
Money that is a prepayment: income tax withholding, federal and state. It is an estimate collected during the year. If too much was collected you receive the difference back after filing, and if too little was collected you owe the remainder. Either way the withheld figure on your stub is not the tax you owe, it is what has been paid toward it so far.
Money that settled an obligation: a garnishment or support order lowered a balance you owed to somebody else, which is a different outcome from the money vanishing.
That is the honest version of "where did my salary go", and it is more useful than a percentage, because it tells you which parts of the gap are decisions and which parts are not.
Why two people on the same salary see a different gap
Briefly, because it explains a common frustration. The tax lines depend on what you told your employer on your Form W-4 and on the state you work in. The deduction lines depend on which benefits you elected and at what level. The result is that identical gross pay routinely produces different net pay, without anything being wrong on either stub.
Nothing about that difference is something to copy from a coworker. The elections behind it are personal, and the paperwork behind them belongs with your employer's payroll department and, for the tax side, with the IRS or a tax professional.
Gross pay still matters, for a few narrow things
Net pay is the number your household actually receives. Gross pay is not decorative, though, and three things are calculated from it rather than from your take-home figure.
Your overtime rate, where you are eligible for it, is derived from your regular rate of pay rather than from your net. Percentage based benefits, such as a retirement contribution set at a percentage of pay or an employer match expressed the same way, are applied to gross. And lenders, landlords and application forms often ask for gross annual income, which is why the number on your offer letter and the number in your account can both be described as "your income" in different rooms on the same day.
The one that matters for planning is which figure your household spends from, and that question has a clear answer set out in budgeting from gross or net income.
What the gap does not include
Your gross pay is not what you cost your employer, and your stub may show this explicitly. Employers pay their own share of Social Security and Medicare, plus unemployment insurance and often a large part of your health premium. Many stubs print those employer amounts for information.
They are not part of your gross to net gap and they never touch your take-home pay. Adding them into the arithmetic is one of the two common reasons a stub appears not to reconcile, and it is worth knowing before you start subtracting lines.
When the gap changes and nothing was announced
Net pay moving without a raise or a new election is normal more often than people expect, and the stub usually shows why. Common causes include a benefit that started or ended mid period, an annual premium change at open enrollment, a change in hours or overtime inside the period, a bonus period being withheld against differently from an ordinary period, a new calendar year resetting annual figures, and a percentage based contribution moving because gross moved.
The way to find it is comparison rather than calculation: put the stub from before the change beside the stub from after it, and look for the line that moved. If a smaller than expected deposit is what caused you to look in the first place, the timing side of that problem, rather than the payroll side, is what our guides on why you run out of money before payday and building a one paycheck buffer deal with. And if the amount changes because the number of checks in the month changed, that is a pay frequency question covered in weekly, biweekly and semimonthly pay.
If the comparison does not explain it, the question goes to payroll, who can see the inputs that produced both stubs.
FAQ
What is the difference between gross pay and net pay? Gross pay is everything you earned in the pay period before deductions. Net pay is what remains after taxes and other deductions, and it is the amount deposited to your account.
Where does the money between gross and net actually go? To several different places: a tax authority as a prepayment against your tax bill, the federal social insurance programs, an insurer for any coverage you elected, an account in your own name for retirement or health savings, and any third party named in a court order.
Is my tax withholding the same as my tax bill? No. Withholding is money collected during the year toward a bill that is calculated when you file. The final figure can be higher or lower than what was withheld.
Are retirement contributions part of the money I lose to deductions? They reduce your take-home pay, but the money stays yours in a retirement account. It changes where your money sits rather than how much of it you own.
Why is my coworker's take-home pay different on the same salary? Because tax withholding depends on the information each of you gave your employer and on where you work, and deduction lines depend on which benefits each of you elected. Different stubs on identical gross pay are ordinary.
Sources: Internal Revenue Service, for Form W-4, Form W-2 and the treatment of federal income tax withholding as a payment toward a bill settled at filing, named as documents rather than quoted, read 2026-09-07. No tax rate, wage threshold, contribution limit or dollar figure appears on this page. Those change from year to year, and the IRS publishes the current ones.